Job costing for a service business: a complete worked example
Track labour, materials, supplier and travel costs against one job, then compare the result with the quoted price.
Give every cost the same job reference
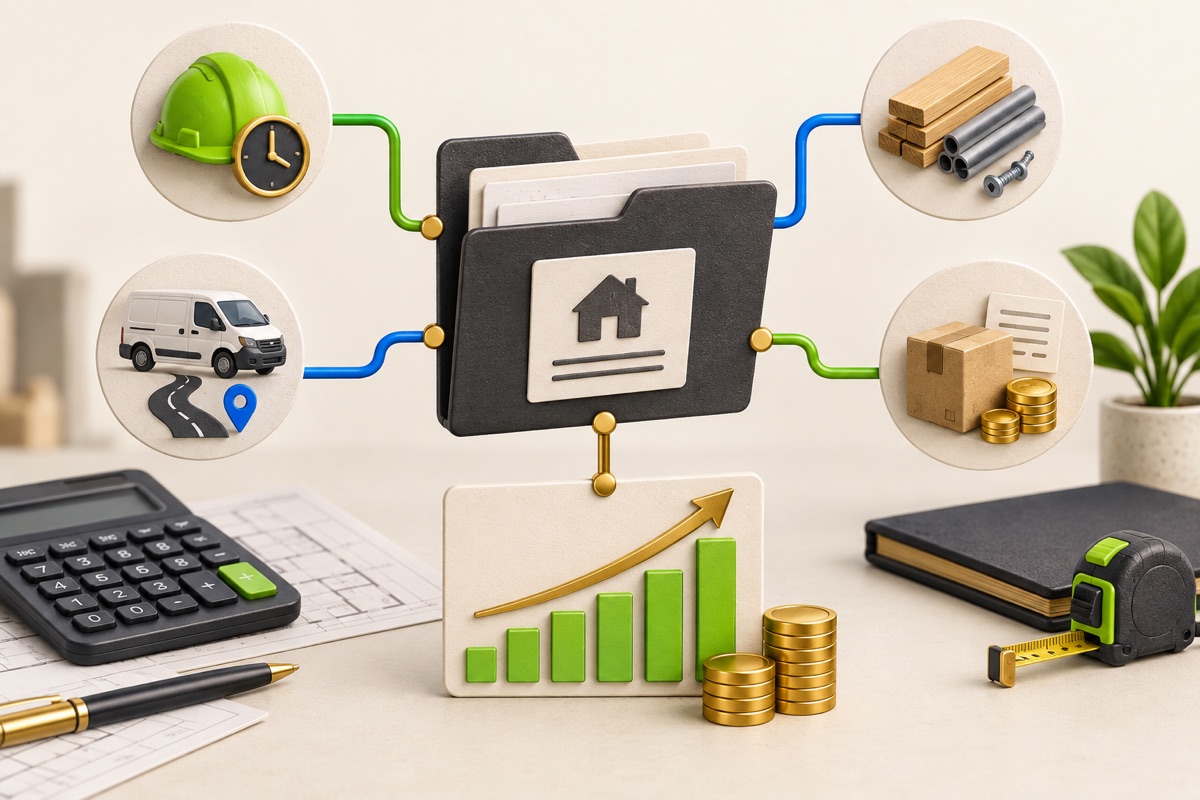
Job costing answers whether a particular job produced the gross result you expected. Record the accepted price and attach labour, materials, supplier charges and travel to the same job. A monthly expense total cannot explain which type of work is underpriced.
Choose a consistent basis for labour cost. An employee wage, a loaded employment cost and a customer billing rate are different numbers. Document what your model includes so the result can be compared over time.
Work through a $2,500 service job
Assume a fictional accepted price of $2,500 before tax. Labour is 18 hours at an internal cost of $35 per hour, or $630. Materials cost $720, a specialist supplier costs $260 and travel allocated to the job is $90. Direct job cost is $1,700.
The simplified gross result is $2,500 minus $1,700, or $800. Gross margin on selling price is $800 divided by $2,500, which is 32%. Markup on direct cost is $800 divided by $1,700, approximately 47.06%. Neither percentage includes overhead, finance, tax or the cost of idle capacity.
- Accepted job price: $2,500.
- Labour: 18 × $35 = $630.
- Materials: $720.
- Supplier: $260.
- Travel: $90.
- Direct cost: $1,700; gross result: $800.
Compare the estimate with the actual job
Suppose the estimate allowed 14 labour hours but the job used 18. The extra four hours cost $140 on this basis. Record the reason: incomplete site information, rework, access delay or an approved scope change. The explanation matters more than a red variance badge.
If the customer approved extra work, connect the variation to the revised price. If the business absorbed the cost, preserve that fact for future quotations. Do not rewrite the original estimate to make the variance disappear.
Use patterns to improve the next quotation
One job does not establish a reliable average. Compare similar completed jobs and separate exceptional events. UtilityHub Business can keep planned and actual costs beside the job so owners can review profitability without exposing financial controls to every role.
Use the Project-cost Estimator before quoting and the Profit-margin Calculator to test the proposed price. These tools calculate from inputs; they do not predict demand or guarantee profit. The quality of the decision depends on complete cost records.
Most relevant guides
Selected by shared topic, search intent and connected tools.